Why the UK Agricultural Drones Market Is Growing Fast


The UK agricultural drones market has some impressive growth forecasts. But what is actually happening on the ground? In England, more drones are receiving equipment grant support for greenhouse whitewashing. Dealers are also adding agricultural drones to their product ranges and expanding their servicing options. These changes suggest that it is becoming easier for farmers and contractors to access the equipment and get support after purchase.
So, where could the next wave of growth come from? There are already opportunities in equipment sales, software, and drone services. For anyone considering buying an aircraft or entering the market as a dealer, these are areas worth watching. Drone spraying could create another source of demand, but routine pesticide applications still depend on products gaining approval for use on drones in the UK.
How Fast Is the UK Agricultural Drones Market Growing?
Two research firms expect fast growth, although they start from very different estimates. Grand View Research’s UK outlook estimates revenue at US$262.2 million in 2025 and projects US$970.7 million by 2033. It forecasts 18% compound annual growth from 2026 to 2033. MarketsandMarkets’ UK outlook starts at US$108.5 million for 2025 and projects US$457.4 million by 2030, with 33.3% annual growth over that period.
The forecasts agree on direction. Their 2025 estimates are more than US$150 million apart, and their growth rates cover different years. Both reports cover equipment and related software or services, so their figures describe a wider business than aircraft sales alone. Our global agricultural drones market overview explains how the products and services a report counts can change the headline number.
There’s a smaller change we can measure directly. In Defra’s Farming Investment Fund data, Table 8, the number of drones in contracted or closed projects for applying greenhouse whitewash rose from 12 in the 2024 grant round to 21 in the 2025 round. That’s nine more aircraft backed through the same English grant scheme. It measures take-up within that programme. A comparable series for UK-wide farm drone sales or service revenue would be needed to put a rate on growth across the whole market.
What Is Driving Demand for Agricultural Drones in the UK?
The greenhouse figures show that some businesses will commit to equipment when it fits a job they already do. For other growers, it can take longer to free up the money. Defra’s farm income figures put average farm business income on English cereal farms at £49,500 in 2024/25 and provisionally forecast £17,000 for 2025/26. For farms under that kind of pressure, the cost of getting started matters.
- Grants make some purchases easier to fund. England’s 2025 grant specification covered drones for putting whitewash on glasshouses. The 2026 round broadened the same item to drones for applying authorised products such as seed and fertiliser. It listed £14,476 against a reference equipment cost of £36,190. For an eligible business budgeting for a drone, the advertised grant could cover up to 40% of that reference cost. The 2026 application window has closed.
- Hiring opens the market to farms with occasional work. A grower might need one extra pass when harvest is running late. Hiring a contractor to spread cover crop seed can make sense for that one job. Buying and maintaining an aircraft takes more work to pay off. When one contractor serves several growers, those small orders can together support demand for equipment, training and parts.
- Local suppliers make buying and owning equipment easier. Drone Sales UK added an agricultural division to its business, offering agricultural drone packages and in-house servicing. Meanwhile, AutoSpray Systems reported a network of 50 pilots in its September 2025 evidence to Parliament. Those examples show dealers and operators putting resources into UK service capacity. That matters to a buyer who needs training before a first season or a repair during a short working window.
How Are UK Farms Using Agricultural Drones?
- Cover crop seeding is one job UK growers can already book. At West Burton in Northumberland, a contractor spread seed into standing wheat three to four weeks before harvest. That gave the cover crop more time to establish. The farm plans to extend the approach to all the cover crops it sows ahead of its 2027 spring barley.
- Crop scouting creates a market for images and reports. Low Altitude lists one-off visits and monthly monitoring in southern England, with a £280 site fee plus a per-hectare charge. That gives growers the option to pay for one field report first. If it helps the agronomist decide where to look, they can book follow-up visits to see how the same patches change. Once the report points to an issue that needs crop protection, the work a drone operator can sell changes.
Can Farmers Spray Crops with Drones in the UK?
Routine commercial pesticide spraying by drone still has no UK authorisations, according to the Health and Safety Executive’s guidance on aerial spraying. Approved trials require an Extrapolated Trials Permit, an Aerial Spraying Permit covering each application, and authorisation from the Civil Aviation Authority (CAA). For a buyer, that rules out basing an equipment purchase on routine pesticide contracts today.
Seed spreading can already be sold under a suitable CAA Operational Authorisation to drop material. That’s why a drone with a spray tank and a spreader can have very different uses in the UK, depending on what the operator plans to apply.
Will the UK Agricultural Drone Market Keep Growing?
Crop monitoring during the growing season and seeding around harvest give service companies work at different times of year. If farms come back for both, operators have more yearly revenue to put towards aircraft, software and pilot training. Repeat business matters especially when funding changes. In its response to the Farming Profitability Review, the government said it had no current plans for another standalone round of England’s equipment scheme. A business that can make the numbers work from customer orders is better placed to invest when there’s no grant window open.
Wider crop protection approvals could give the market a second route to growth. The UK Pesticides National Action Plan commits to reviewing the benefits and drawbacks of drone application and considering changes to the rules. The milestone to watch is an actual commercial product authorisation. That would let operators price work for the approved use and see how many growers are ready to book it.
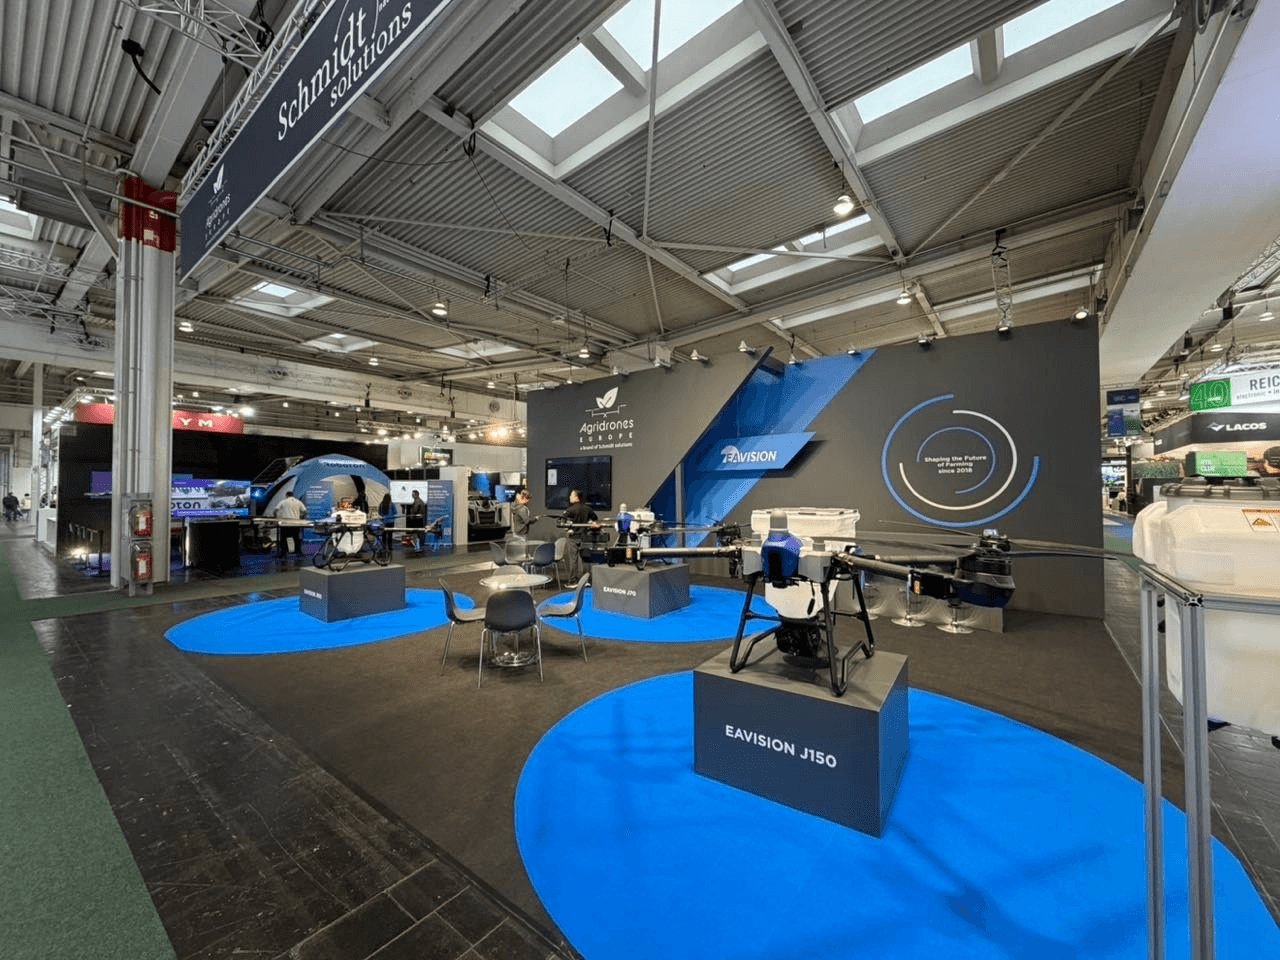
For farmers and contractors considering an aircraft purchase, local demand matters more than a national market forecast. If spreading work is picking up in your area, for example, think about the equipment and support your operation will need. You can browse the EAVISION agricultural drone range to compare models and their capabilities. For businesses already working with growers or contractors, there may also be an opportunity to expand into this market. You can apply to become an EAVISION dealer and explore a potential partnership.
FAQs
Is the UK Agricultural Drones Market Already Growing at 18%?
The 18% is Grand View Research’s forecast for annual compound revenue growth from 2026 to 2033. A UK-wide historical series would be needed to calculate the actual rate.
What Counts as Revenue in the Agricultural Drone Market?
Market reports can include aircraft, software, and services. A new drone sale and a grower paying a contractor for a scouting flight are both ways the market can generate revenue.
Did the 2026 Drone Equipment Grant Apply Across the UK?
England’s Farming Equipment and Technology Fund was open to eligible businesses based and registered in England. Its 2026 application window closed in May.
Can UK Farmers Hire a Drone for Cover Crop Seeding?
Yes. An operator can offer the service with a CAA Operational Authorisation that covers dropping seed. Cover crop seeding is already available through UK contractors.
What Would Open Up Commercial Pesticide Spraying?
A product would need commercial authorisation for drone application. Operators would also have to meet the aerial spraying permit and aviation requirements for the work.